On 2 November 2026, the regulatory capacity of electronic-money wallets increased across the West African Monetary Union. BCEAO Instruction No. 020, signed on 8 October, entered into force and replaced two provisions of the 2015 framework governing electronic-money issuers.
The most visible change is a higher ceiling. An identified customer may now hold up to CFAF 4 million with the same issuer, up from CFAF 2 million. Monthly top-ups with that issuer may total CFAF 15 million, compared with CFAF 10 million under the 2015 rules.
The reform does more than enlarge wallets. It also changes how the assets backing outstanding electronic money may be allocated. The operational implications therefore extend to limit management, liquidity, fraud controls and daily reconciliation.
Two limits measuring different things
The first ceiling applies to a stock. At any point in time, an identified customer’s total electronic-money holdings with one issuer must not exceed CFAF 4 million unless BCEAO has granted prior approval.
The second applies to inflows. Top-ups made by the customer with that issuer may not exceed CFAF 15 million in aggregate during the same month, unless an exemption has been approved.
| Indicator | 2015 rule | Rule effective 2 November 2026 | Change |
|---|---|---|---|
| Maximum holdings per identified customer and issuer | CFAF 2 million | CFAF 4 million | x2 |
| Aggregate monthly top-ups per issuer | CFAF 10 million | CFAF 15 million | +50% |
| Minimum share of backing assets held in demand deposits | 75% | 65% | -10 percentage points |
Neither threshold is a per-transaction payment or transfer limit. A customer may top up a wallet several times, spend or transfer part of the funds, and top it up again. The balance may remain below CFAF 4 million while monthly top-ups approach CFAF 15 million.
This distinction directly affects the limit engine. A control based only on the current balance cannot track cumulative monthly funding. A monthly accumulator, on the other hand, does not prevent the real-time balance from exceeding its own ceiling.
The ceiling applies per issuer, not per instrument
The new instruction requires an issuer to aggregate all instruments held by the same customer. Two wallets, prepaid cards or other electronic-money products issued by the same institution do not create two separate allowances.
The issuer therefore needs a consolidated customer view. Different instruments must be linked to a reliable identity, balances must be combined and top-ups accumulated across the portfolio.
Where customer records, channels or product platforms are fragmented, the main risk is not only an obvious excess. Duplicate identities, incomplete product matching or delayed updates between systems can also allow a customer to breach a limit without any individual platform detecting it.
The ceilings do not apply to distributors and electronic-money acceptors acting in a professional capacity. This reflects their liquidity and collection needs, but it also makes accurate account classification and status-change controls more important.
Greater capacity requires stronger controls
A higher permitted balance can support larger payments, professional collections or the temporary storage of more value in a wallet. It also increases the amount exposed when an account is compromised.
Issuers should therefore review at least six controls:
- aggregation of every instrument linked to the same customer;
- separate monitoring of balances and monthly top-ups;
- alerts for sudden changes in value or behaviour;
- stronger authentication for selected high-risk transactions;
- detection of structuring and circular movements;
- time-bound management of exemptions approved by BCEAO.
The instruction retains a process for exceeding the standard ceilings with prior central-bank approval. The request must state the reason, duration and amount involved, together with the additional transaction-monitoring and risk-management measures. BCEAO may impose conditions, restrict the duration or withdraw the approval.
An exemption should therefore not become a permanent switch in a product configuration. It needs an expiry date, a customer-specific ceiling, supporting documentation, an audit trail and a controlled return to the standard limit.
Customer funds must still be fully backed
The second major change concerns the assets backing electronic money in circulation.
The 2015 framework required at least 75% of the backing assets to be held in demand deposits. The new instruction lowers the minimum to 65%. Demand deposits, term deposits and specified debt securities remain eligible, while BCEAO may set different allocation limits according to an issuer’s risk profile.
The ten-percentage-point reduction potentially gives issuers more room to allocate funds to permitted assets other than demand deposits. It does not allow them to use customer money freely to finance operating expenses.
Articles 32 and 33 of the underlying framework remain central. The backing funds must be segregated, separately identified and reconciled daily against the electronic-money liability. The value received in exchange for electronic money must remain at least equal to the amount outstanding.
The issue is therefore not simply investment yield. Issuers must preserve the ability to redeem customers at par, manage liquidity outflows and prevent a market-value loss or temporary lack of access to an asset from disrupting redemptions.
What should be monitored after implementation
The impact of the reform should be measured through more than the number of wallets or aggregate transaction value.
Useful indicators include:
- the share of customers using more than 50%, 75% or 90% of the new balance ceiling;
- the concentration of value in high-balance accounts;
- rejected transactions caused by balance or monthly-funding limits;
- the number, value and duration of exemptions;
- duplicate identities and incomplete aggregation across instruments;
- account takeover and fraud rates by balance band;
- reconciliation breaks between outstanding electronic money and safeguarded funds;
- the immediately available share of backing assets and actual redemption times.
These measures would show whether higher limits support genuine economic needs without weakening the protection of customer funds.
A capacity reform with operational consequences
Raising the balance ceiling from CFAF 2 million to CFAF 4 million clearly expands what electronic-money accounts can hold in WAEMU. A CFAF 15 million monthly top-up allowance also recognises that some customers now use wallets for larger and more frequent flows.
The reform’s effect will nevertheless depend on implementation. Issuers must consolidate instruments by customer, separate different kinds of limits, manage exemptions, strengthen high-value account controls and maintain full backing for every unit of electronic money issued.
The customer-facing ceiling is the simplest part of the change. Behind it sit the limit engine, customer identity, fraud monitoring, liquidity, safeguarding and daily reconciliation. The reform should ultimately be assessed across that entire chain.
Sources
- BCEAO: Instruction No. 020 amending electronic-money limits
- BCEAO: full text of Instruction No. 020
- BCEAO: 2015 framework governing electronic-money issuers
- BCEAO: full text of Instruction No. 008-05-2015
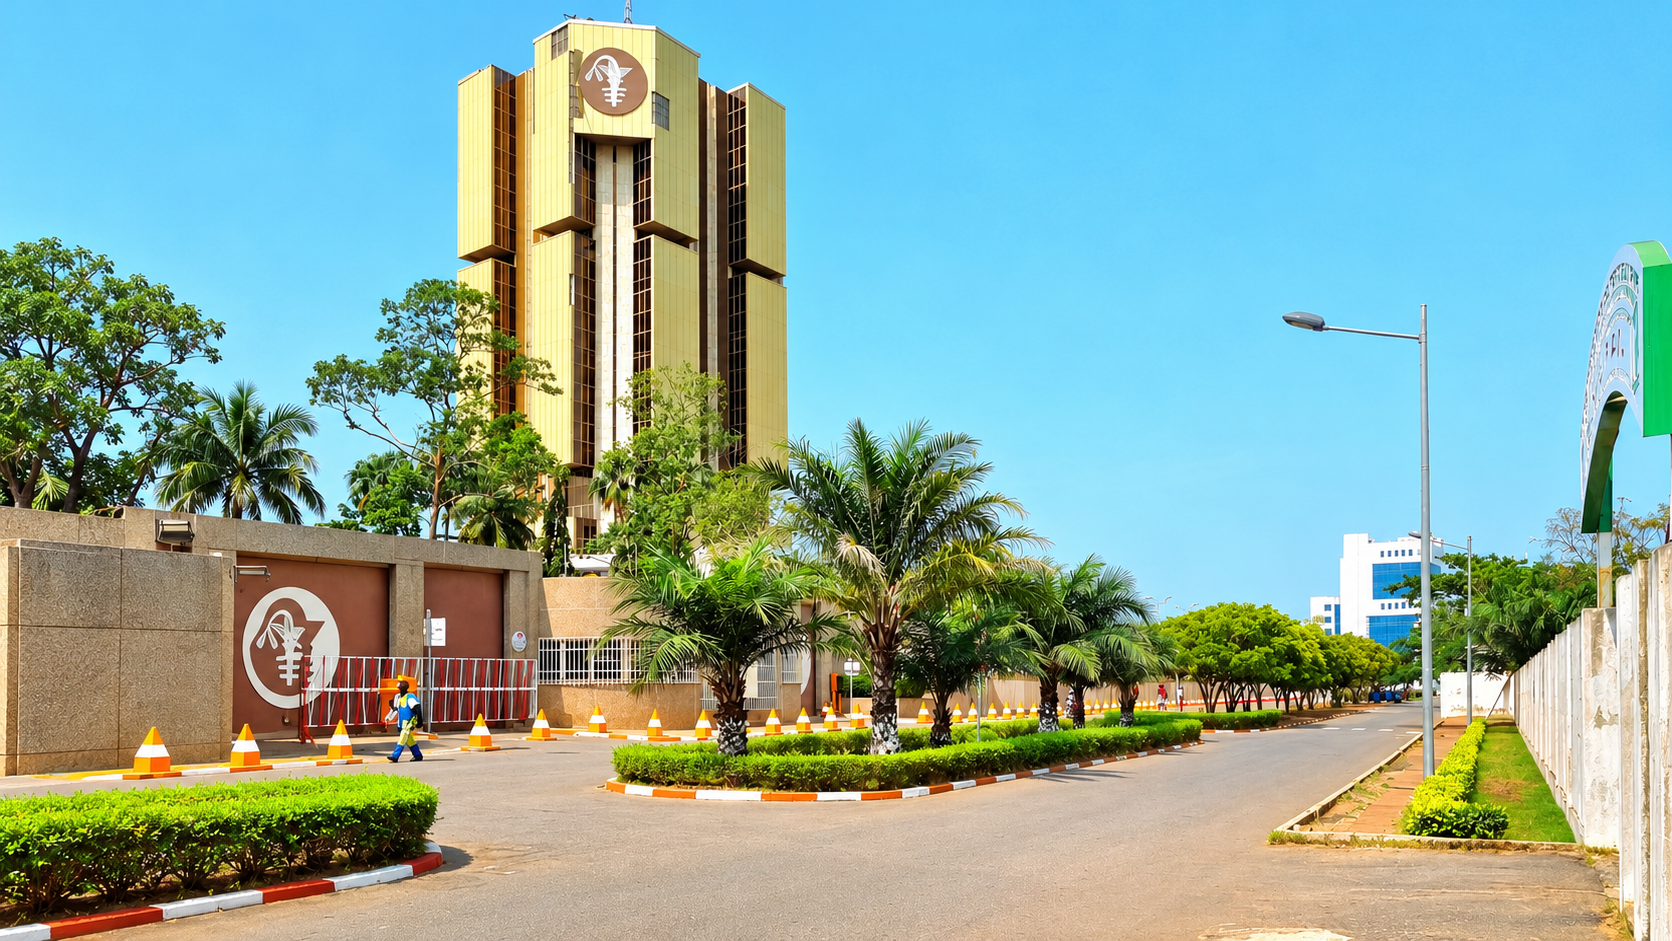
Cover credit: photograph by Edison McCullen, BCEAO headquarters in Lomé, licensed under CC BY 4.0. Image adapted to a horizontal format.