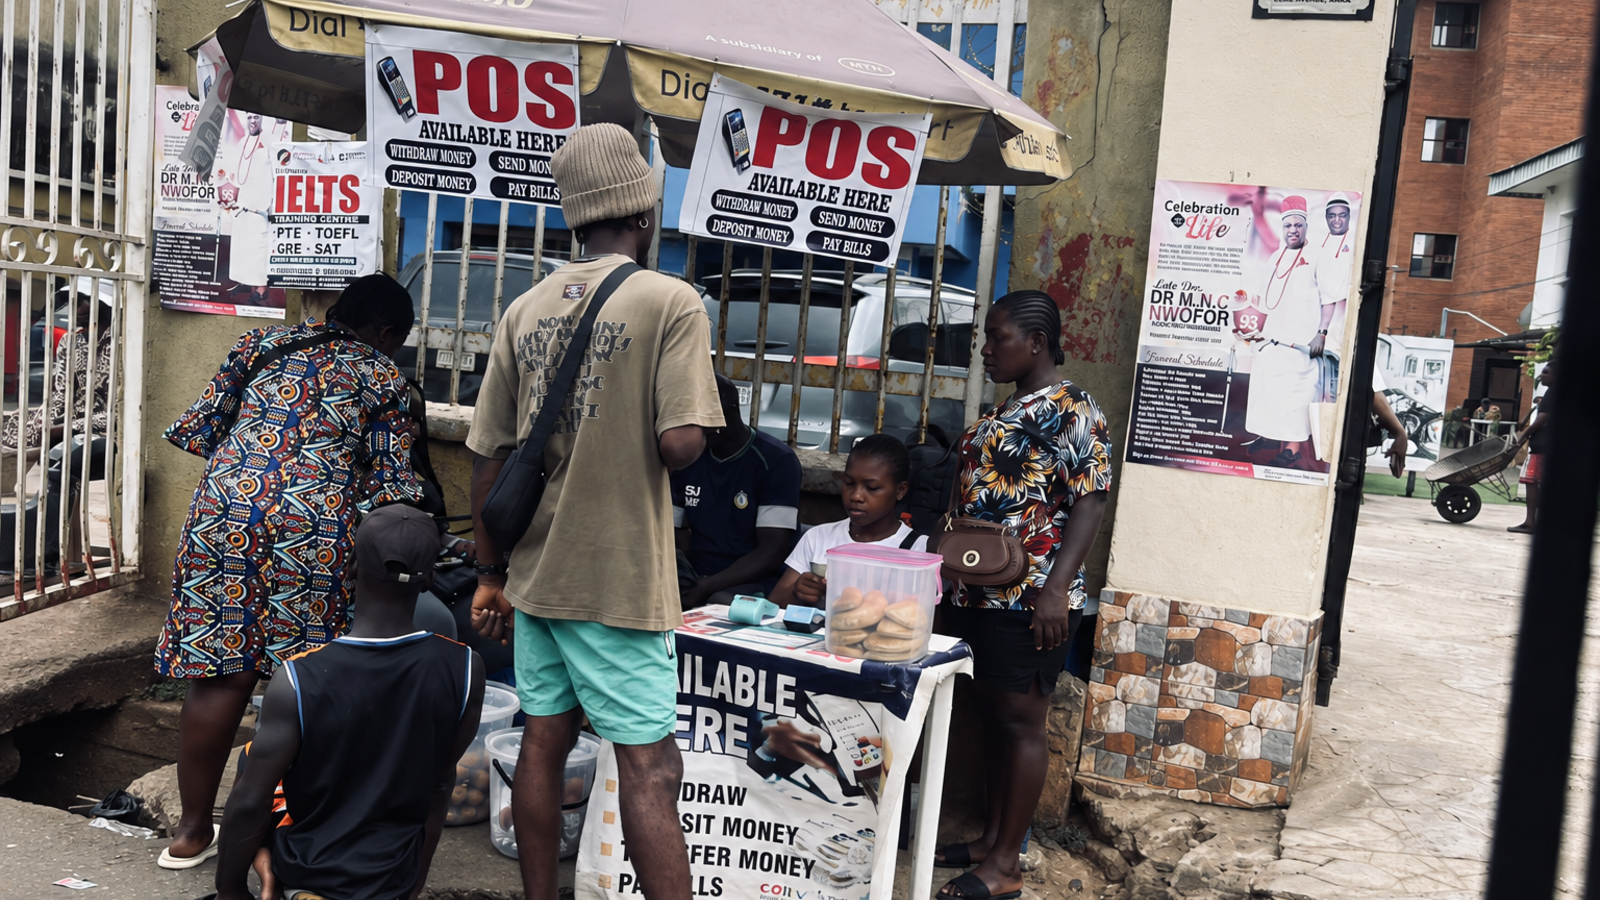
One number stands out in Boston Consulting Group’s Global Payments Report 2026: payments revenue in the Middle East and Africa could rise from $98 billion in 2025 to about $150 billion in 2030. That would represent average annual growth of 8%, faster than the forecasts for North America, Europe and Asia-Pacific. Source: BCG Global Payments Report 2026
The opportunity is significant, but the number needs to be read carefully. BCG groups the Middle East and Africa into one region and does not provide, in the public presentation, a breakdown between the two markets. The $150 billion figure cannot therefore be treated as African revenue alone.
BCG is also describing a revenue pool. It combines income earned across the payments ecosystem, both directly from transactions and through related services. It is neither the value of payments processed nor the revenue of any single company.
That distinction changes the economics. Transaction activity can grow rapidly while revenue per payment falls, technology costs rise or another participant in the chain captures most of the value.
Four numbers that tell different stories
When a bank, fintech or PSP reports growth, four measures are often blended together:
- transaction count;
- total payment value;
- net revenue retained;
- margin after costs and losses.
Consider two platforms that each process 100 million transactions. One charges merchants for selected services, automates reconciliation and keeps fraud losses under control. The other offers free transfers, pays several intermediaries and relies on a large operations team to resolve exceptions. Their volumes are identical. Their financial outcomes may be very different.
A simple way to express payment economics is:
Payment margin = fees + foreign-exchange, liquidity and service revenue - network and processing costs - fraud and disputes - commercial and operating expenses.
This formula does not replace a detailed income statement. It simply shows that volume sits at the beginning of the calculation, while profitability appears at the end.
Instant payments are shifting the business model
BCG points to cash-to-digital migration, instant transfers and wider payment acceptance as regional growth drivers. All three trends are visible across Africa, although they produce different levels of revenue.
In WAEMU, BCEAO presents PI-SPI as an instant service that is free for individuals. A bank or fintech cannot build its entire model around charging for the transfer itself. Value will also need to come from business services, collections, treasury, reconciliation, distribution and products built around the account. Source: BCEAO
Card payments follow a different model. They may generate more gross revenue, while also carrying network, acquiring, authentication, fraud, chargeback and compliance costs. Mobile money adds agent commissions, liquidity management, cash-in, cash-out and distribution-network costs.
Placing all three rails in the same “volume” column hides the main point: their unit economics are fundamentally different.
Where margin disappears
Growth can be bought. Free transfers, cashback and discounted fees can accelerate adoption. The strategy may be sound during a launch, provided management knows the real cost of each additional transaction and when the product is expected to break even.
Margin can also disappear through failure. A declined attempt may consume much of the same technical capacity as a successful payment without generating revenue. Duplicates, unknown statuses, late refunds, reconciliation breaks and chargebacks then create manual work, tie up cash and damage the customer experience.
Network expansion comes with its own price. Connecting more banks, wallets or countries extends commercial reach. Each connection also adds interfaces to monitor, file formats to reconcile, rules to maintain and incidents to resolve.
BCG’s survey of nearly 500 large companies illustrates the pressure: 79% said their payment costs had increased over the previous five years, while fewer than one in ten had reduced them. The sample covers large global companies rather than small African merchants, so it should not be treated as a direct picture of the continent. It still shows that payment growth does not solve the cost question by itself. Source: BCG merchant survey 2026
Seven measures to track alongside volume
A useful view of payment profitability needs operating and financial measures alongside transaction growth:
| Metric | What it shows |
|---|---|
| Net revenue over payment value | Value retained after revenue sharing |
| Cost per successful transaction | Total processing cost, including failed attempts |
| Success and authorisation rates | Share of payment intentions that are completed |
| Net fraud and dispute loss | Remaining cost after recoveries and chargebacks |
| Settlement time and prefunding need | Cash tied up to keep the service operating |
| Automatic reconciliation rate | Share of flows handled without manual intervention |
| Value-added service revenue share | Income from reporting, treasury, compliance and related services |
These measures are most useful when segmented by country, rail, corridor, customer group and use case. A portfolio average can look healthy while one profitable product quietly covers the losses of another.
What the $150 billion forecast really signals
BCG’s forecast points to a clear direction: the regional payments ecosystem is expected to keep expanding. It does not yet show how much of that growth will come from Africa, which rails will grow fastest or which providers will retain the strongest margins.
The forecast is not a measure of financial inclusion either. A low-cost payment can create substantial social value while producing little direct revenue. Higher fees may lift short-term income while slowing adoption or keeping more customers in cash.
For African providers, the practical question is straightforward: after network fees, processing, fraud, disputes, distribution and manual operations, how much value remains from each transaction?
The providers that can answer that question accurately will be better placed to benefit from the growth ahead. Their advantage will come from execution quality, reconciliation and cost control as much as from the transaction volumes they report.
Sources
- BCG: Global Payments Report 2026
- BCG: merchant payments cost and profitability survey
- BCEAO: launch of PI-SPI
- GSMA: State of the Industry Report on Mobile Money 2026
Cover credit: adapted from a photograph by Bigkotech, [Wikimedia Commons](https://commons.wikimedia.org/wiki/File:Pos_agents_when_cash_can_be_transferred,withdrawn.jpg), licensed under [CC BY-SA 4.0](https://creativecommons.org/licenses/by-sa/4.0/deed.en).